Fifty/Fifty Is Fair Only If You Earn the Same
If you are a dual-income couple, run a hybrid setup: one joint account for shared costs, funded in proportion to income, plus a separate personal account each. Once you are married, share goals, and have similar money values, going fully joint is a fine upgrade. Fully separate is the one model I would talk you out of, because it turns every household decision into a negotiation.
Fifty/fifty is the default a lot of couples reach for because it sounds fair. It is fair only when you earn the same. Otherwise one of you quietly pays a much bigger share of their paycheck for the same apartment, and the lower earner feels broke while the higher earner feels fine. Let’s run the numbers.
The Three Models, Defined
You have three options.
- Fully joint. All pay goes into shared accounts. Everything comes out of them. One budget, one set of goals.
- Fully separate. Each person keeps their own accounts. You split bills by sending money back and forth, or by each paying specific bills.
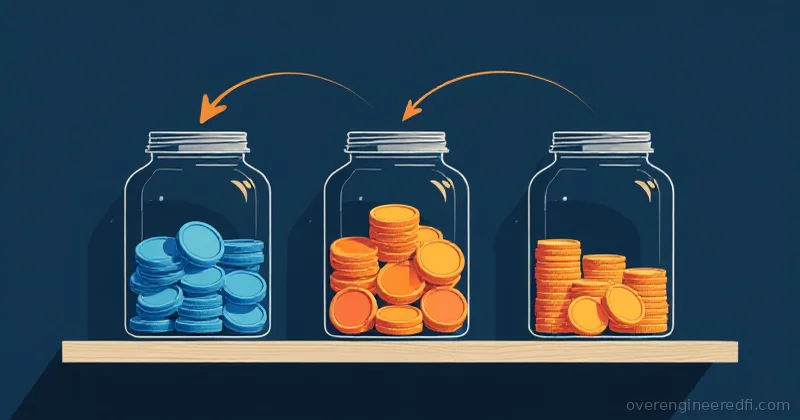
- Hybrid. A joint account pays shared costs. Each person also keeps a personal account that the other person does not audit.
The hybrid is a yours / mine / ours setup. Three buckets, and the rules for each fit on an index card.
The Math: 50/50 vs Proportional
Every number here is a hypothetical example. Swap in your own.
Partner A earns $210,000 a year. Partner B earns $90,000. Combined, that is $300,000, so A earns 70% and B earns 30%. After federal and state tax, 401k deferrals, and benefits, say A takes home $11,500 a month and B takes home $5,000. Your shared costs (rent or mortgage, utilities, groceries, insurance, internet, the streaming services nobody will cancel) come to $6,000 a month.
Model 1: 50/50 split. Each person pays $3,000.
| Partner A | Partner B | |
|---|---|---|
| Take-home | $11,500 | $5,000 |
| Share of $6,000 | $3,000 | $3,000 |
| Left over | $8,500 | $2,000 |
| Share of take-home spent on shared costs | 26% | 60% |
Model 2: proportional split (70/30). A pays $4,200 and B pays $1,800.
| Partner A | Partner B | |
|---|---|---|
| Take-home | $11,500 | $5,000 |
| Share of $6,000 | $4,200 | $1,800 |
| Left over | $7,300 | $3,200 |
| Share of take-home spent on shared costs | 37% | 36% |
Check the math: $8,500 + $2,000 = $10,500, and $7,300 + $3,200 = $10,500. The household has the same total money left either way. The only thing that moves is who holds it.
Under 50/50, B spends 60% of their take-home on the shared pile while A spends 26%. B has $2,000 for savings, fun, student loans, and everything else. Under the proportional split, both of you spend about 36 to 37% of your take-home on shared costs. Same lifestyle, same apartment, and B has $1,200 more every month.
One detail: the 70/30 comes from gross pay, and take-home pay was 69.7% and 30.3% in this example. Rounding to 70/30 is fine. If you want to be exact, split by net pay, but nobody has ever saved a relationship by debating $18 a month.
Model 3: fully joint. Both paychecks land in one account. The household has $16,500 coming in, $6,000 going to shared costs, and $10,500 left to split between savings goals and fun. The split of who “paid for what” stops existing, which is the point.
The Yours / Mine / Ours Setup
Here is the mechanical version of the hybrid. It takes about an hour to set up, then runs without you.
- Open a joint checking account at a bank with no monthly fee. This is “ours.”
- Set up payday auto-transfers. Each paycheck lands in your personal checking account. A scheduled transfer then moves your proportional share to the joint account the same day. In the example, A sends $2,100 and B sends $900 on each of two paychecks a month (the amounts come from the $4,200 and $1,800 above, halved).
- Point shared bills at the joint account. Rent or mortgage, utilities, groceries, insurance, internet, childcare. If both of you use it and neither of you gets to veto it, it goes here.
- Keep personal spending in personal accounts. Gym, hobbies, your gaming rig, gifts for your partner (so the surprise survives), and the third monitor you do not need.
- Pick a fun-money number each. Equal dollar amounts keep it simple. In the example, each of you might get $500 a month, no questions, no explanations. The rule that makes this work is “no questions.” If one person has to justify a $90 keyboard, you built a worse budget with extra steps.
- Add a joint savings goal. Emergency fund, house down payment, vacation sinking fund. A share of the money left over after shared costs flows there on payday too. If you want a model for the labels, sinking funds work well here.
Do a 20 minute check-in once a month. Look at the joint account balance, adjust the transfer if rent goes up, and move on. When someone’s income changes, update the percentages. A raise for A moves the split from 70/30 to something like 72/28, and you adjust two auto-transfers.
Why Fully Separate Fails
Fully separate looks clean on paper. Then you move in together and one of you buys the couch, the other pays the vet, and someone has to track who owes whom for the third time this quarter. It also hides things. Nobody sees the full picture of retirement savings, debt, or a surprise tax bill. You are running two small companies that share a lease.
It works for couples who got together late, have kids from prior relationships, or have strong reasons to keep estates apart. Even then, add a joint account for shared costs. That is the hybrid.
What Does Not Merge, No Matter What You Do
Some things stay individual whatever your bank account setup looks like.
Credit. There is no joint credit score. Each of you has your own credit reports and your own scores. Marriage does not merge them. A joint credit card or joint loan appears on both reports, and both of you are liable for the full balance, so a late payment hurts both. Opening a joint checking account is not a credit event. A joint card or mortgage is.
Retirement accounts. A 401(k), a traditional or Roth IRA, and an HSA are always owned by one person. You cannot open a joint IRA. You cannot name your spouse as a co-owner of your 401(k). What you can do is coordinate the contributions, which is where the spousal IRA comes in below.
Beneficiary designations. Your 401(k), IRA, HSA, and life insurance all pay whoever is named on the form, not whoever your will says. If you named your college roommate in 2014 and never updated it, your roommate may be in for a nice surprise, and your spouse may not be. Federal law gives a spouse first claim on most 401(k) plans unless the spouse signs a waiver, but IRAs, HSAs, and life insurance get no federal spousal protection, so outside the community property states below, the form usually wins. Check every beneficiary form this month. Your 2 AM self will thank you.
The 2026 Rules Couples Get Wrong
The spousal IRA
You can open an IRA for a spouse who earns little or nothing. The rules, from IRS Publication 590-A: you must file a joint return, and each spouse’s contribution is limited to the lesser of the IRA limit or the couple’s combined taxable compensation, minus the other spouse’s IRA contributions.
For 2026, the IRA contribution limit is $7,500, up from $7,000 in 2025, per the IRS. So if A earns $210,000 and B stays home with the kids, A can put $7,500 into A’s IRA and $7,500 into B’s own IRA. That is $15,000 of household IRA money, even though B has no paycheck. B’s IRA is B’s property, titled in B’s name.
Roth eligibility depends on your joint modified adjusted gross income. For 2026, the phase-out range for married couples filing jointly is $242,000 to $252,000, according to the IRS. At $300,000 of combined pay, the couple in our example sits right at the edge. MAGI comes after pre-tax 401(k) deferrals, so if both max their 401(k)s ($24,500 each for 2026) they land around $251,000, inside the phase-out, with a small partial Roth contribution left. Any raise pushes them out, so the backdoor Roth is the realistic route.
The HSA family limit is shared
For 2026, the HSA contribution limit for family coverage is $8,750 (self-only is $4,400), per IRS Revenue Procedure 2025-19. The gotcha: it is one limit for the couple, not one each (the only exception is the $1,000 catch-up for each spouse 55 or older, which goes into that spouse’s own HSA). IRS Publication 969 says that if either spouse has family HDHP coverage, both spouses are treated as having family coverage, and the limit is split equally between you unless you agree on a different split.
So if both of you put $8,750 into separate HSAs, you have over-contributed by $8,750, and that excess owes a 6% excise tax every year it stays in the account. Pick the split, set payroll deductions to match, and add them up, employer contributions included. There is no joint HSA, so each spouse’s share goes into an account in that spouse’s own name.
FDIC coverage on joint accounts
Deposit insurance covers $250,000 per depositor, per bank, per ownership category. Joint accounts are their own category. According to the FDIC, each co-owner of a joint account is insured up to $250,000 for the combined amount of their interests in all joint accounts at that bank, and shares are presumed equal.
That means a couple’s joint account can hold $500,000 at one bank and be fully covered. Each of you can also hold $250,000 in a single-owner account at the same bank, insured separately. If your total cash is below those figures, you are covered. If it is above, split it across banks.
Community property states
Nine states use community property rules: Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, and Wisconsin (per IRS Publication 555). In general, income earned during the marriage belongs half to each spouse, whatever name is on the paycheck. This affects how property is divided, how a married-filing-separately return is prepared, and what a spouse’s creditors can reach. If you live in one of these states, talk to a local attorney or a CPA before you assume your separate account is legally separate.
Married filing jointly vs separately
Most married couples file jointly. Joint brackets are exactly twice as wide as separate ones, so a couple with uneven incomes like A and B pays less by pooling, and many credits and deductions are cut off or reduced if you file separately. Filing separately has real uses, such as keeping your return apart from a spouse with tax debt or a messy return, but it is the exception. Run both through tax software before you pick it. In community property states, filing separately gets more involved still.
Gifts between spouses
Married couples have an unlimited marital deduction. Moving $400,000 from your account to your spouse’s is not a taxable gift, as long as your spouse is a US citizen. If your spouse is not, the rule changes: for 2026, the first $194,000 of gifts to a non-citizen spouse is excluded from gift tax, per IRS Revenue Procedure 2025-32. Above that, you file Form 709.
If You Are Not Married
Unmarried couples do not get the marital deduction. The annual gift tax exclusion for 2026 is $19,000 per recipient, per the same IRS revenue procedure. If you put $60,000 into an account that your partner can withdraw from, and your partner spends it on themselves, that is a gift of $60,000, and because it is over $19,000 you need to file Form 709. You probably owe no tax, because the lifetime basic exclusion for 2026 is $15,000,000. But the paperwork exists, and a joint account turns “paying more than my share of the rent” into a gift-tax question faster than you would expect.
Two more things that surprise unmarried couples:
- Titling matters. The name on the deed or the car title decides who owns it. If you pay the down payment and only your partner is on the deed, the IRS can treat it as a gift, and on paper you own nothing. If the relationship ends, getting that money back can take a lawyer.
- No automatic inheritance. In most states, intestacy law favors spouses and relatives, not partners. Without a will, beneficiary forms, or a trust, your partner may inherit nothing from you.
If you are unmarried and buying a home, put both names on the deed and sign a written agreement about who paid what. A lawyer’s fee costs less than a dispute.
A Decision Framework
Start at the top. Stop when a line matches you.
- Married, similar money values, shared goals? Go fully joint if you both want it. Keep a small personal allowance each so you do not have to explain a $40 purchase.
- Married or not, two incomes, any gap between them? Use the hybrid with a proportional split. This is the default.
- Incomes within about 10% of each other? The proportional math lands close to 50/50, so split evenly and skip the spreadsheet.
- Remarrying, kids from a prior relationship, or a large separate estate? Use the hybrid and get an estate attorney to review titling and beneficiaries.
- Unmarried? Use the hybrid, keep the joint account to shared costs, and keep gifts under $19,000 per person for 2026 unless you are ready to file Form 709.
- Either of you carries large debt? Decide before you merge accounts whether the debt is joint or individual, and keep it in the individual’s name.
Then do three things this week: set up the payday transfers, update every beneficiary form, and put the monthly check-in on your calendar. Twenty minutes a month costs less than a single argument about who paid for the couch.
Common Questions
Does opening a joint bank account affect your credit score?
No. A joint checking or savings account does not appear on your credit reports and does not change your score. Joint credit cards, loans, and mortgages do appear on both reports.
Can you open a joint IRA or 401(k) with your spouse?
No. An IRA or 401(k) is always owned by one person. Spouses cannot co-own either account type. A married couple filing jointly can still fund an IRA for each spouse, including a non-working spouse, if their combined taxable compensation covers both contributions.
Is a joint account insured by the FDIC?
Yes. The FDIC insures joint accounts up to $250,000 per co-owner at each bank, and the shares are presumed equal. A two-person joint account can therefore be insured up to $500,000 at one bank. That coverage is separate from each person’s single-owner accounts at the same bank.
Do you have to merge finances after getting married?
No. No law requires you to combine bank accounts after you marry. Many couples use a hybrid setup instead. Your tax filing status, inheritance rights, and property laws still change when you marry, so review beneficiaries and titles even if your accounts stay separate.