Wash Sale Traps Your Broker Won't Catch
Your broker only flags wash sales inside one account. IRA buys, spouse trades, ESPP and RSU vests can kill a harvested loss. See the math and the fix.
All the articles with the tag "investing".
Your broker only flags wash sales inside one account. IRA buys, spouse trades, ESPP and RSU vests can kill a harvested loss. See the math and the fix.
Own crypto anyway? Cap it at 1% to 5% of investable assets, pick the number before you buy, use a cheap wrapper, and rebalance on a rule. Worked math included.
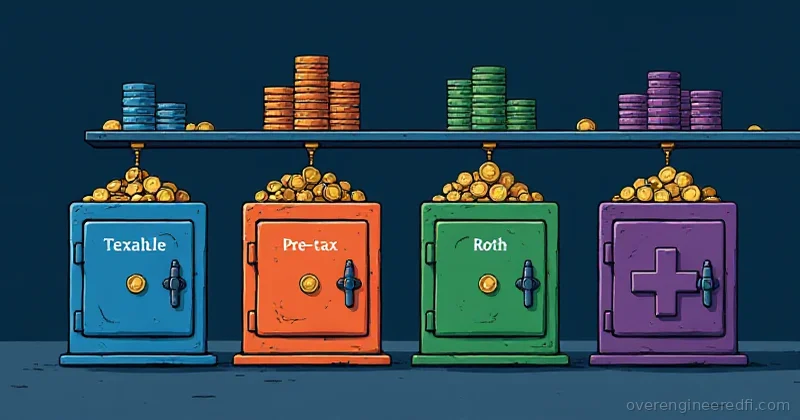
Asset location puts bonds, REITs, and stock funds in the right account. See the worked math on a $300k portfolio, a ranked table, and the gotchas that break it.
Index target-date funds cost 0.08% to 0.12%. Their lookalike active cousins cost 0.68%. See the dollar math, the taxable-account trap, and when DIY beats a TDF.
The 3.8% Net Investment Income Tax hits high earners with dividends, gains, and rent. See the thresholds, worked examples, and legitimate ways to cut the bill.
Empower's free dashboard is good for net worth and fee checks. On $500K, its 0.89% fee plus fund costs trails a three-fund portfolio by $305K over 20 years.
Direct indexing costs 3 to 13 times more than an index ETF and only pays off through tax-loss harvesting. Here's the break-even math for tech-worker incomes.
Exchange funds defer tax on a concentrated stock position for 7 years but cost 1%+ a year and require $500k+ minimums. Here's when they actually beat selling.
If you give to charity and hold appreciated stock, writing a check is the worst option. Donating shares skips capital gains tax and still deducts full value.

A normal bond fund does nothing when inflation spikes: the coupon is fixed and inflation eats it. I Bonds and TIPS exist to solve exactly that problem.

Betterment and Wealthfront charge about 0.25% to automate a portfolio you could build yourself for less. The real dollar cost, and who it is worth paying for.

Rebalancing is risk control, not a return booster. How drift actually happens, the calendar-plus-band approach, and how to do it without a big tax bill.