Wash Sale Traps Your Broker Won't Catch
Your broker only flags wash sales inside one account. IRA buys, spouse trades, ESPP and RSU vests can kill a harvested loss. See the math and the fix.
All the articles with the tag "taxes".
Your broker only flags wash sales inside one account. IRA buys, spouse trades, ESPP and RSU vests can kill a harvested loss. See the math and the fix.
Own crypto anyway? Cap it at 1% to 5% of investable assets, pick the number before you buy, use a cheap wrapper, and rebalance on a rule. Worked math included.
Tender offer or secondary sale for your startup shares? See how ISOs, NSOs and RSUs are taxed, what fees and ROFR delays to expect, and how much to sell.
DCFSA vs the child care credit for 2026: a $7,500 dependent care FSA saves $2,816 to $3,416 at $260k to $450k income, the credit just $1,200. See the math.
72(t) SEPP lets you tap an IRA at 45 with no 10% penalty, but it locks you in until the later of 5 years or 59½. See all three methods with 2026 numbers.
Your RSU vest gets a flat 22% withheld no matter your tax bracket. See how a single $130,000 vest can leave you owing $14,400 more than was withheld next April.
Joint, separate, or hybrid accounts? Worked math for a $210K and $90K couple, the yours/mine/ours setup, and the 2026 limits on IRAs, HSAs, and gifts.
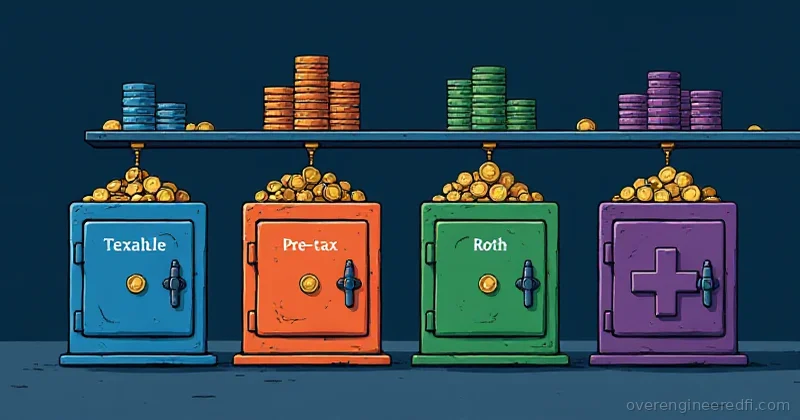
Asset location puts bonds, REITs, and stock funds in the right account. See the worked math on a $300k portfolio, a ranked table, and the gotchas that break it.
The 3.8% Net Investment Income Tax hits high earners with dividends, gains, and rent. See the thresholds, worked examples, and legitimate ways to cut the bill.
The Rule of 55 lets you pull from your 401k penalty-free after leaving your job at 55 or later. Learn who qualifies, the rollover trap, and the real tax math.
A $180K W-2 offer needs a 1099 rate of about $214K a year, or $116 an hour, to break even. Here is the full payroll tax, benefits, and bench-time math.
Non-qualified deferred compensation can cut your tax bill, but the balance is an unsecured IOU from your employer. Here is when an NQDC plan is worth the risk.